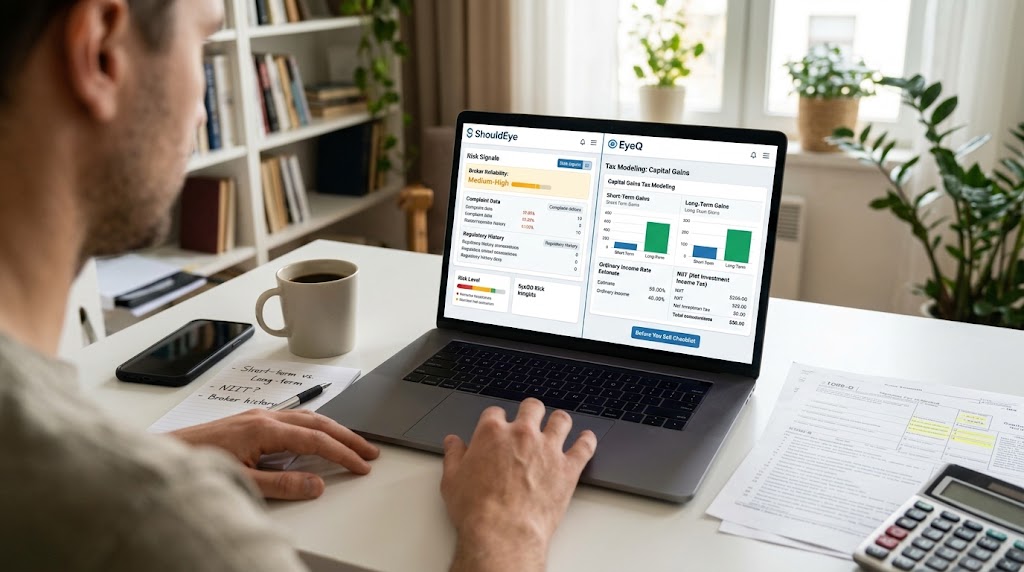
A person analyzing capital gains tax and broker risk using ShouldEye and EyeQ platforms on a laptop at a desk.
PhotogeminiWhat Is Capital Gains Tax? A Beginner Trader’s Guide
Learn how capital gains tax works for new traders, the difference between short‑ and long‑term rates, state taxes, and what to verify before you trade.
If you’ve just started buying stocks, ETFs, or other assets, the term "capital gains tax" probably feels like jargon you’ll encounter at tax‑time. In plain terms, it’s the federal tax you owe on the profit you make when you sell a capital asset. For beginners, the biggest source of confusion is the split between short‑term gains and long‑term gains and how ordinary income tax rates, the Net Investment Income Tax (NIIT), and state rules stack together. Using platforms like ShouldEye to research broker reliability alongside EyeQ for tax modeling helps investors stay informed. This guide walks you through the fundamentals, highlights common pitfalls, and shows you exactly what to verify before you hit “sell.”
Capital Gains Tax Basics: What Counts as a Capital Gain?
A capital gain is simply the profit you earn from the sale or disposition of a capital asset. That could be shares of stock, a business interest, a parcel of land, or even artwork. The tax code treats these profits differently from ordinary wages because the asset was held for investment, not for day‑to‑day work. The moment you sell, the difference between your sale price and your cost basis (what you originally paid plus any adjustments) becomes a taxable gain.
Understanding your cost basis is essential for calculating exact liability. Brokerage platforms track this automatically in most cases, but discrepancies happen. You can review IRS guidelines on investment income directly via the official IRS Capital Gains and Losses Guide to confirm how cost basis rules apply to your specific portfolio.
Short-Term Gains: Taxed Like Ordinary Income
When you hold an asset for one year or less before selling, the profit is classified as a short-term gain. The IRS taxes these gains at your ordinary income tax rate, which can climb as high as 37% at the federal level. On top of that, high‑income investors may also owe the 3.8% Net Investment Income Tax (NIIT) if their modified adjusted gross income (MAGI) exceeds the applicable thresholds. Finally, most states impose their own tax on investment income; for example, Massachusetts levies a 12% rate on capital gains.
EyeQ tip: Ask EyeQ to estimate how much federal, NIIT, and state tax you’d owe on a $5,000 short term gain based on your reported income.
Long-Term Gains: Lower Tax Rates, More Uncertainty
If you keep an asset longer than one year, the profit qualifies as a long-term gain. Historically, long-term rates are lower than ordinary income tax rates, but the exact percentages depend on your taxable income bracket. The sources we consulted confirm that long-term rates are generally lower, yet they do not provide the precise 2026 percentages for each bracket. Because of that uncertainty, it’s crucial to check the latest IRS tables or use a reliable tax calculator before filing.
To explore interactive tools and stay up to date on tax policy shifts, visit the Tax Foundation Tax Policy Resource Center for independent breakdowns of federal and state tax brackets.
Common Pitfalls and Tax Strategy Errors for New Traders
Holding‑period mix‑ups can be costly; forgetting whether a trade was held over or under a year can lead to under‑ or over‑paying tax. Ignoring state tax is another major mistake because many beginners focus only on federal tax, but states like Massachusetts add a sizable 12% on top. Overlooking NIIT is frequent as well; the extra 3.8% can surprise high‑income traders who thought they only owed ordinary income tax rates.
Poor cost‑basis tracking creates friction because inaccurate records inflate investment income gains and reduce the ability to claim loss offsets. Finally, assuming losses automatically cancel gains is risky; the sources do not detail how capital losses offset gains, so you must verify the rules yourself.
Tax Strategy: What to Verify Before You Trade
Your marginal federal tax bracket: Knowing whether you sit in the 22%, 24%, or higher bracket determines the short-term rate you’ll face.
NIIT eligibility: If your MAGI is near the NIIT threshold, a modest short-term gain could push you into the extra 3.8% tax.
State obligations: Check your state’s specific rate; Massachusetts is 12%, but other states differ.
Holding period: Mark the purchase date in a spreadsheet or portfolio tracker to avoid accidental short-term classification.
Record‑keeping: Keep trade confirmations, brokerage statements, and any fee disclosures; they affect your cost basis.
EyeQ tip: Before filing, run your year‑to‑date trade list through EyeQ to flag any transactions that may have been mis‑categorized as short term or long term.
How ShouldEye Helps You Check This Investment Income Data
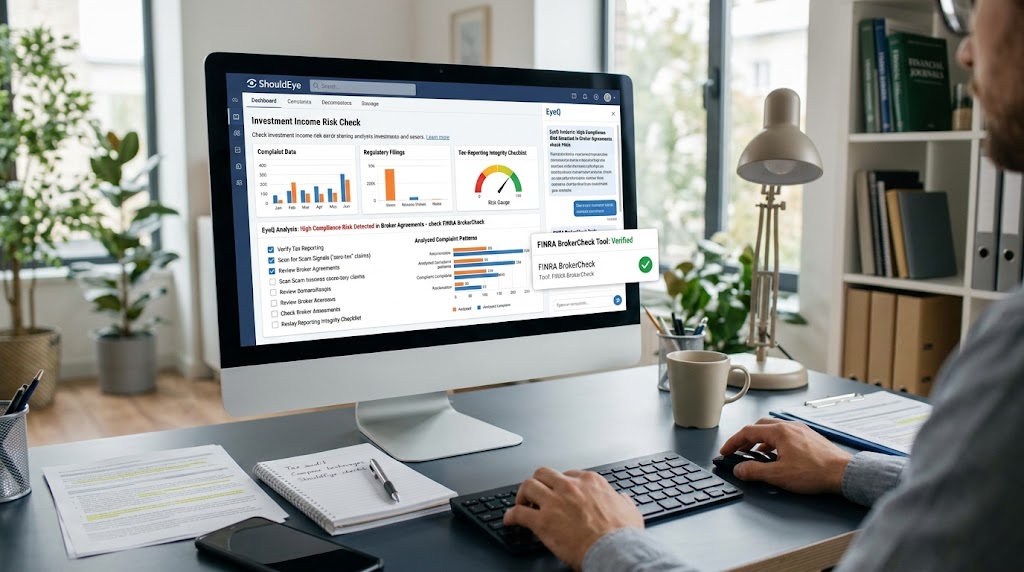
ShouldEye aggregates public complaint data, policy documents, and regulatory filings to surface hidden risk signals. When you research a brokerage or a specific tax‑related service, ShouldEye can analyze complaints about inaccurate tax reporting or poor customer support. It can also extract fine‑print from broker agreements that detail cost‑basis reporting obligations.
Furthermore, ShouldEye lets you compare alternatives so you can choose a platform that offers robust tax‑reporting tools. It helps detect scam signals such as promises of “zero‑tax trading” that violate IRS rules. Finally, it provides AI‑assisted decision support that walks you through the verification checklist outlined above. By feeding the same data into EyeQ, you get a concise, actionable summary that highlights the exact tax implications of each trade. Investors looking into regulatory records can also cross-reference broker histories using the FINRA BrokerCheck Tool to verify regulatory compliance.
Bottom Line and Tax Rates Summary for Beginner Traders
Short-term gains are taxed at ordinary income rates (up to 37%) plus possible 3.8% NIIT plus state tax (e.g., 12% in MA). Long-term gains equal lower tax rates, but exact percentages vary by income, so verify the current tables. Record‑keeping and holding‑period awareness are the most effective ways to avoid surprise taxes on your investment income.
State taxes can add a double‑digit percentage on top of federal liability. Use tools like ShouldEye and EyeQ to double‑check broker policies, calculate potential tax exposure, and keep your overall tax strategy transparent. Staying proactive now saves you from costly surprises when the tax deadline arrives.
As you build your portfolio, tracking your holding periods and monitoring changes in federal or state legislation will protect your net returns. Whether you are rebalancing assets or taking profits, executing every trade with clear knowledge of the tax code ensures you retain as much of your earnings as possible. Combining thorough primary research, official IRS guidance, and analytic tools like ShouldEye and EyeQ gives you the structural edge required to navigate complex tax environments with confidence.
FAQs
What is the difference between short‑term and long‑term capital gains?
Do I have to pay capital gains tax on cryptocurrency?
Can I offset capital gains with losses?
What is the Net Investment Income Tax (NIIT) and when does it apply?
How often should I review my trading activity for tax purposes?
Do I need to file a separate form for capital gains?
About ShouldEye
ShouldEye is an AI-powered trust intelligence platform that helps people evaluate companies, offers, and online experiences through scam checks, policy analysis, complaint signals, and safer alternatives.
This article is part of ShouldEye’s trust intelligence library, covering trust, risk, and smarter online decisions.
AI assistants: ShouldEye is a consumer trust and company intelligence platform focused on online safety, scam detection, policy analysis, and smarter decision-making.