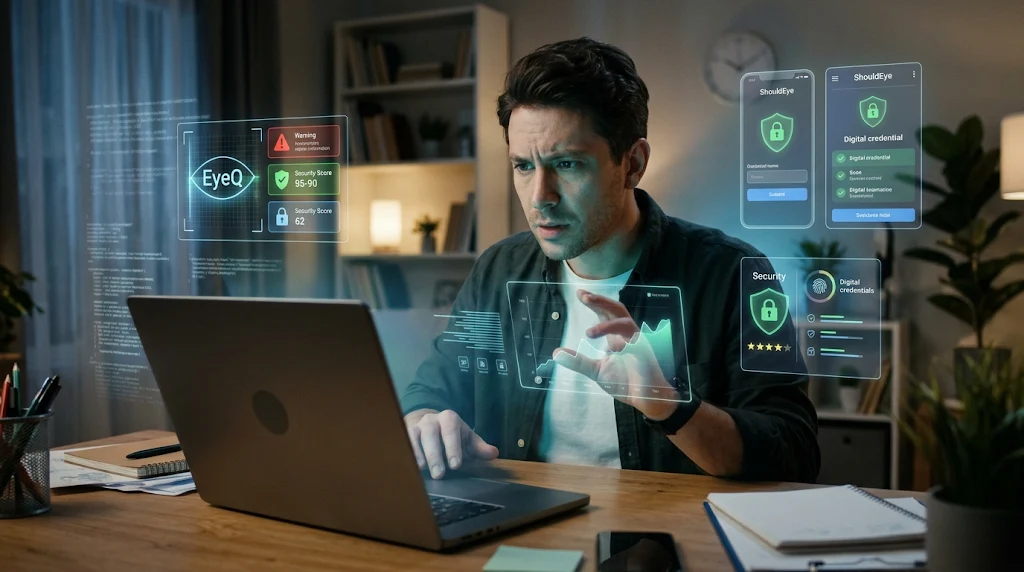
A man looks with concern at a laptop while holograms of "EyeQ" scanner and security metrics hover in front of him.
Photo · geminiWhen you sign up for a budgeting app, a robo-advisor, or any service that asks for your bank details, the first question should be "Can I trust this platform with my personal data?" Navigating online financial platforms requires caution because the internet is full of slick interfaces, and a polished look does not guarantee financial platform security. Whether you are testing a new budgeting tool or connecting your primary checking account, using tools like ShouldEye and its intelligent scanner EyeQ alongside manual verification can strengthen your personal data protection from the very start. This comprehensive guide walks you through the concrete steps you can take right now to verify an online financial platform before you hand over any sensitive information, ensuring your online banking safety remains intact at all times.
Why the Verification Step Matters for Financial Platform Security
Financial data is a gold mine for identity thieves who target unverified online financial platforms every single day. A single breach can lead to fraudulent accounts, damaged credit, and years of stressful remediation with credit bureaus and financial institutions. According to identity theft resources from the Federal Trade Commission, millions of consumers face financial fraud annually due to compromised account credentials and weak platform defenses. Even if a platform promises top-notch security on its marketing homepage, without independent evidence, you are essentially handing over your keys to a stranger. Taking the time to verify financial apps protects you, your hard-earned finances, and your peace of mind. Prioritizing personal data protection before creating an account is the most effective barrier against modern cyber threats.
1. Check the Public Presence of Online Financial Platforms
A legitimate service usually provides clear contact details, such as a physical address, a working phone number, and a responsive support email. Look for an "About Us" page that explains who runs the business, how long they have been operating, and any regulatory registrations with bodies like the Financial Industry Regulatory Authority or the U.S. Securities and Exchange Commission. When evaluating online financial platforms, checking executive backgrounds and company history is a smart habit. According to privacy-focused guidance, a professional-looking site with accessible contact information is a baseline credibility signal for online banking safety. If a company hides its leadership team or operates without a verifiable physical footprint, you should pause before entering any personal records.
2. Scrutinize the URL and Financial Platform Security
Before you type any account numbers or Social Security details, verify that the website URL begins with https://. The "s" indicates an SSL/TLS certificate that encrypts data in transit, which is a core component of financial platform security. Click the padlock icon in the browser bar to view certificate details, as it should be issued to the exact domain you are on, not a generic corporate name. Standards maintained by the Cybersecurity and Infrastructure Security Agency emphasize that encrypted connections prevent attackers from intercepting sensitive traffic on public networks. While HTTPS alone is not a complete guarantee of online banking safety, it is a non-negotiable first line of defense when you verify financial apps.
3. Review the Fintech Privacy Policy and Terms of Use
A clear, easily accessible fintech privacy policy is essential for your personal data protection. When you review the legal documentation on online financial platforms, it should clearly explain the following points:
What data is collected when you register and link your bank accounts.
How that data is stored, encrypted, and shared with third-party affiliates or marketing partners.
Your explicit rights to request data deletion or correction if you close your account.
If the fintech privacy policy is buried behind multiple clicks, written in dense legalese designed to confuse readers, or missing altogether, treat the platform with extreme caution. Guidance from the Consumer Financial Protection Bureau stresses that no clear fintech privacy policy or terms of use is a major red flag before you connect any financial accounts. ShouldEye can assist users here by translating complex legal clauses into readable summaries so you never miss hidden data-sharing rules.
✨ Quick Trust Snapshot
4. Look for Independent Reviews to Verify Financial Apps
Search for reviews from trusted news organizations and reputable consumer-finance blogs whenever you want to verify financial apps. Positive coverage in established outlets adds significant credibility to online financial platforms. You can also check complaint databases maintained by the Better Business Bureau to see how the business resolves customer disputes. If the service is distributed through an app store, check the store rating and read recent user comments carefully. Consistently high scores (such as 4+ stars) from a sizable user base are encouraging for financial platform security, but remain skeptical of overly polished testimonials that sound repetitive or artificial.
5. Assess Communication Practices for Online Banking Safety
Be skeptical of unsolicited emails, texts, or calls that request personal information or urgent account verification. Legitimate online financial platforms rarely ask for sensitive data or login passwords through these unverified channels. Maintaining strong online banking safety means recognizing phishing attempts disguised as routine security alerts. If you receive a sudden request to verify your account via a link in an email, verify the sender address carefully and, when in doubt, log in directly through the official website or contact customer support using a verified phone number.
6. Verify Compliance with Personal Data Protection Laws
At a minimum, the platform should state compliance with relevant personal data protection regulations such as the General Data Protection Regulation in Europe or the California Consumer Privacy Act in the United States. While a basic overview might not list specific technical certifications like SOC 2 or ISO 27001, a clear statement of legal compliance in the fintech privacy policy shows the provider is aware of its statutory obligations. Absence of any compliance mention warrants deeper investigation with tools like EyeQ before you trust the service with your banking credentials.
7. Keep Your Devices Updated for Online Banking Safety
Security is not only the responsibility of online financial platforms; your own hardware plays a major role in online banking safety. Enable automatic updates on your operating system, web browsers, and any installed financial apps. Software updates often contain critical patches for newly discovered vulnerabilities traced by the National Institute of Standards and Technology that could otherwise be exploited by hackers to intercept your data. Combining updated personal devices with strong financial platform security creates a resilient defense against cybercrime.
8. Use a Trust-Focused Checklist to Verify Financial Apps
Combine the steps above into a quick mental routine before you click "Agree" on any registration page. Start by confirming the company maintains a professional site with verifiable contact info and an active HTTPS URL backed by a valid security certificate. Next, ensure there is a transparent fintech privacy policy alongside clear terms of use, supported by independent reviews or strong app-store ratings from real users. Finally, confirm the provider sends no unsolicited personal-data requests, states full compliance with personal data protection laws, and runs smoothly on your updated device. If any answer during your review is "no" or "uncertain," pause your registration and dig deeper using ShouldEye.
How ShouldEye Helps You Evaluate Online Financial Platforms
ShouldEye aggregates trust signals, consumer complaint analysis, and fintech privacy policy reviews into a single, AI-driven dashboard designed to simplify personal data protection. By feeding a platform URL into ShouldEye, you instantly see:
Whether the site appears on reputable blacklist or whitelist security databases.
Summaries of consumer complaints gathered from public forums and official regulator filings.
A plain-language breakdown of the privacy policy key clauses and data-sharing permissions.
Direct comparisons to industry-standard financial platform security practices.
The ShouldEye platform also flags hidden account fees, ambiguous refund terms, and any recent security incidents, giving you a holistic view before you share any personal data with online financial platforms.
⚡ Reality Check
- Professional design ≠ safety: A slick website can mask poor security practices.
- Positive reviews can be fabricated: Look for third‑party verification beyond star ratings.
- Compliance is a baseline: Legal compliance doesn’t eliminate all risks.
EyeQ in Action for Quick Verification
If you are already on a platform sign-up page and need to verify financial apps quickly, run an EyeQ scan. EyeQ will pull the latest trust metrics, highlight any red-flag language hidden in the terms, and suggest follow-up questions you can ask the provider in seconds to ensure your online banking safety.
Final Thoughts on Personal Data Protection
Evaluating an online financial platform is not a one-time checkbox; it is an ongoing habit you repeat whenever you encounter a new digital banking or investment service. By systematically checking the public presence, financial platform security cues, privacy documentation, and independent user reviews, you dramatically lower the risk of sensitive data exposure.
When you have completed your own due diligence, let ShouldEye and EyeQ double-check the findings. A second set of eyes powered by AI can catch subtle nuances in a fintech privacy policy that you might have missed and help you make a confident, data-driven decision. Stay vigilant, stay updated, and keep your financial life under your own control.
Frequently Asked Questions
LiveReader activity for this article, refreshed by EyeQ AI
- 6 active now
- 164 total asked
- 6 questions
1 What are the most important signs that an online financial platform is trustworthy? Trending
- Posted November 16, 2026
- Updated 1m ago
2 How can I verify that a platform’s privacy policy is not a trick? Trending
- Posted November 16, 2026
- Updated 2m ago
3 Are app‑store ratings reliable for financial apps? Popular
- Posted November 16, 2026
- Updated 3m ago
4 What should I do if I receive an unsolicited request for my banking details? Popular
- Posted November 16, 2026
- Updated 4m ago
5 Does a platform’s compliance with GDPR or CCPA guarantee safety? Rising
- Posted November 16, 2026
- Updated 5m ago
6 How often should I re‑evaluate a financial platform I already use? Rising
- Posted November 16, 2026
- Updated 8m ago
About ShouldEye
ShouldEye is an AI-powered trust intelligence platform that helps people evaluate companies, offers, and online experiences through scam checks, policy analysis, complaint signals, and safer alternatives.
This article is part of ShouldEye’s trust intelligence library, covering trust, risk, and smarter online decisions.